Same Bet, Different Tax: Does The UK's New Gambling Tax System Add Up? | Analysis
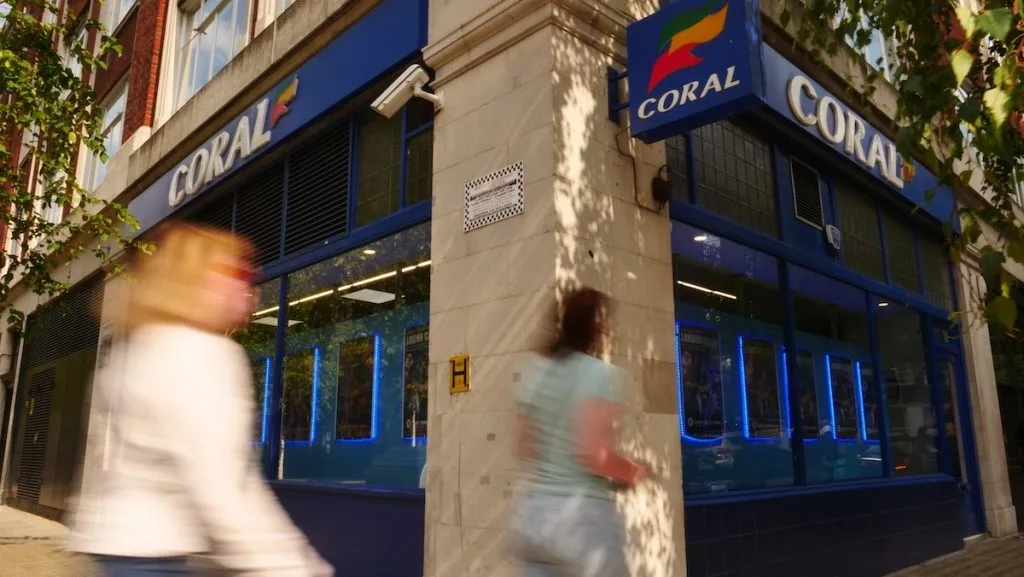
From April 2027, most sports bets placed online in the UK will be subject to a 25% General Betting Duty on the bookmaker's profits. Place the same bet in a high street betting shop, and the rate stays at 15%.
If you change the sport to horse racing, things are different yet again. A racing bet placed in a betting shop remains subject to 15% General Betting Duty, just like other sports. However, bookmakers also pay the 10% statutory Horserace Betting Levy on their relevant UK racing profits, creating what the government calls a ‘de facto’ 25% rate. Online racing bets are treated the same way.
So why does the UK's new gambling tax system differentiate not only between where a sports bet is placed, but also what sport the customer is betting on?
Online Sports Betting To Be Taxed at 25% From 2027
The latest major gambling tax reforms were announced in the 2025 Budget. The headline changes were:
- Remote Gaming Duty to increase from 21% to 40% in April 2026.
- A new 25% remote betting rate within General Betting Duty will apply from April 2027, excluding UK horse racing.
The government specifically excluded bets placed inside betting shops. These remain at 15%, both those placed over the counter and on Self-Service Betting Terminals.
This distinction is important. During its consultation on gambling taxation, the government pointed to four reasons for the distinction between remote and land-based betting duty:
- The growth of remote betting
- The gradual decline of land-based betting
- The higher costs of running a betting shop
- The greater employment numbers for physical premises
In short, the government decided there should be a tax advantage to taking a sports bet in a physical betting shop rather than remotely, which makes sense. With rent, business rates, utilities, and shop staff to pay, the overheads are higher. But that’s only one side of the story.
Is Remote Sports Betting More Harmful?
There is another justification running throughout the government's gambling tax reforms: gambling-related harm.
Remote Gaming Duty was almost doubled to 40%. That decision came partly because online casino games and slots are associated with some of the highest levels of gambling-related harm.
The government had previously considered bringing remote betting and gaming together under a single tax. But it rejected that approach because the two have different characteristics and risk profiles. Yet the decision to separate remote and in-person betting seems less about harm and more about the economics of running a betting shop.
It’s clear that gambling tax appears to be doing several jobs at once. It’s raising revenue, it’s an attempt to recognise differences in gambling harm, and it’s also a way to identify contributions to employment. Then, there’s horse racing.
Why Is Horse Racing Different?
Horse racing betting differs from almost all other sports betting in the UK in two ways. These differences exist largely because horse racing has a unique relationship with betting. A huge portion of its revenue comes directly from gambling, so in order to reflect that, some ‘leeway’ has been built into the tax system.
The first difference is that remote bets on UK horse racing are exempt from the new 25% remote betting rate. Instead, they will remain subject to the 15% General Betting Duty.
The government's explanation is simple. British racing already has its own statutory funding mechanism. Bookmakers pay the Horserace Betting Levy on their British racing business.
The current rate is 10% on relevant profits, alongside the 15% General Betting Duty rate. The government says that this combination of GBD at 15% and HBL at 10% creates an ‘effective’ 25% rate for British horse racing.
The next difference emerges when that bet is placed in a betting shop. Like other sports bets, it remains subject to 15% GBD, but unlike almost all other sports, the bookmaker must also contribute to the Horserace Betting Levy.
A football bet placed in a shop will remain subject to 15% GBD. A horse racing bet placed in the same shop will remain subject to 15% GBD, but the bookmaker also contributes to the Horserace Betting Levy. For a total that the government described as ‘de facto 25%’. In other words, the same amount as the new remote betting duty.
That means the GBD advantage deliberately preserved for land-based betting is effectively offset on British horse racing by the separate levy.
There’s a third and final differentiator for horse racing (and greyhound racing in this case): on-course bookmakers. If you bet on course, there’s no GBD for the bookie to pay at all.
So, with racing, where you place the bet really does matter: online and betting-shop bets carry the same effective burden, while taking the bet all the way to the racecourse removes GBD altogether.
Betting Shops: Love Them or Loathe Them?
There’s an interesting tension brewing around betting shops. Government policy appears to be pulling them in two different directions.
On the one hand, betting shops are protected from the new 25% rate, in order to recognise their contribution to employment and offset some of their larger overheads.
On the other, the government is making it easier for local authorities to prevent new betting shops from opening.
Prime Minister Andy Burnham announced in August that the government intends to scrap the Gambling Act's ‘aim to permit’ provision.
Under current rules, licensing authorities should generally permit gambling premises where applications are consistent with the Gambling Act and relevant licensing objectives. Under the proposed new rules, councils would have greater freedom to reject new betting shops where there are concerns about their impact on local areas.
That sits somewhat awkwardly alongside the tax argument. While betting shops are being protected from the higher remote rate partly because of their contribution to jobs and the high street, the government has simultaneously identified their unchecked spread as part of the problem facing some town centres.
The two policies aren’t necessarily incompatible. The government can believe existing betting shops support jobs and high streets, while also believing councils should have greater control over where new ones open.
Yet, when you bring in talks of Machine Games Duty, the waters muddy even further.
Could Higher Machine Games Duty Undermine the Betting Shop Advantage?
Machine Games Duty is now at the centre of another gambling tax row. No increase has been confirmed yet, but the government is reportedly considering raising the standard MGD rate from 20% to 40%.
For sports betting shops, gaming machines are an important revenue source. In fact, the betting industry argues that a substantial increase would make many shops financially unviable.
Jennings Bet CEO Greg Knight has warned that close to 100 of the company's shops could be at risk if MGD rises sharply. The British Horseracing Authority has gone substantially further, arguing that a 40% standard rate could ultimately result in thousands of betting shop closures.
While these are industry forecasts rather than established outcomes, there seems to be policy tension here.
The lower betting duty rate for land-based bookies now seems to work like this:
- Tax saved on sports bets to contribute to overheads and employment costs.
- On British racing, that advantage is effectively offset by the separate Horserace Betting Levy.
- Gaming machine revenue could then face a substantially higher duty burden.
While those three policies all make sense in isolation, when viewed as a whole the policy logic is much harder to understand.
So, Does the New Gambling Tax System Add Up?
There is undoubtedly a rationale behind every part of Britain's new gambling tax structure.
- Remote gaming: Taxed most heavily because it is associated with higher levels of harm and has grown the most rapidly.
- Online sports betting: Taxed more heavily than retail because remote businesses can operate with lower physical overheads and do employ fewer people locally.
- Retail sports betting: Taxed the same as at present, because of local economic contribution.
- Horse Racing: Receives quite different treatment in part because of its special relationship with betting, and also because bookmakers already fund the sport through a statutory levy.
- Machine Games Duty: The government believes there’s a greater propensity for problem gambling, and it should therefore contribute more.
All of these have a defensible rationale in isolation, but it’s exceptionally hard to find a single principle tying them together.
The UK taxes gambling not just for harm, but for operating costs, market growth, high street employment, and even the sport itself.
It is trying to raise revenue, discourage certain products, protect physical businesses, support British racing and recognise decades-old funding arrangements, all at the same time.
That is not to say that any individual tax rate is wrong. But, from April 2027, two customers can place essentially the same sports bet with the same bookmaker and trigger very different tax treatment depending on whether they use an app, walk into a shop, or head to a racecourse.
If the aim is a ‘fair, modern and sustainable’ gambling tax system, as the government describes it, the difficult part may not be explaining each rate separately. It may be explaining why they all belong in the same system.
-
Same Bet, Different Tax: Does The UK's New Gambling Tax System Add Up? | Analysis
-
Jumpman Gaming Wins Landmark £13 Million RGD Tax Case Against HMRC
-
Portugal Seal Nations League Last Eight Place
-
Northern Ireland vs Georgia Prediction, Odds & Tips: NI Promotion Charge Continues
-
Max Verstappen Wins Delayed Bahrain Grand Prix In Malaysia
-
Wales vs Denmark Prediction, Odds & Betting Tips: Both Teams To Score